


Vertical AI Companies are Delivering the ROI
If you recently read the headlines, this is how the AI market looks:
OpenAI raised $110 billion in early 2026, the largest private fundraising in history.
OpenAI secured a major contract with the US Department of Defense at the expense of its arch-rival, Anthropic.
Meanwhile, Anthropic was declared a supply chain risk by the Department of Defense (War) for trying to impose conditions on the use of its Claude models, and the use of Anthropic’s products was banned government-wide.
Claude rocketed to the top of the App Store charts.
Several leading AI executives traded public attacks.
Hyperscalers project that they may collectively spend close to $700 billion on data center construction this year – much of it funded by debt.
People living near proposed data center sites don’t like this. As a result, protests against the construction of new data centers are gaining steam.
DeepSeek released models that matched frontier performance at a fraction of the training cost, alarming the big model makers.
Read those stories, and you would rightfully conclude that enterprise AI isn’t delivering on its promise. You would be wrong. The noise and drama at the model and infrastructure layer are real. Unfortunately, it crowds out coverage of a huge AI success story:
The ascendance of Vertical AI companies.
What Is a Vertical AI Company?
There are two primary types of companies that operate at the AI application layer:
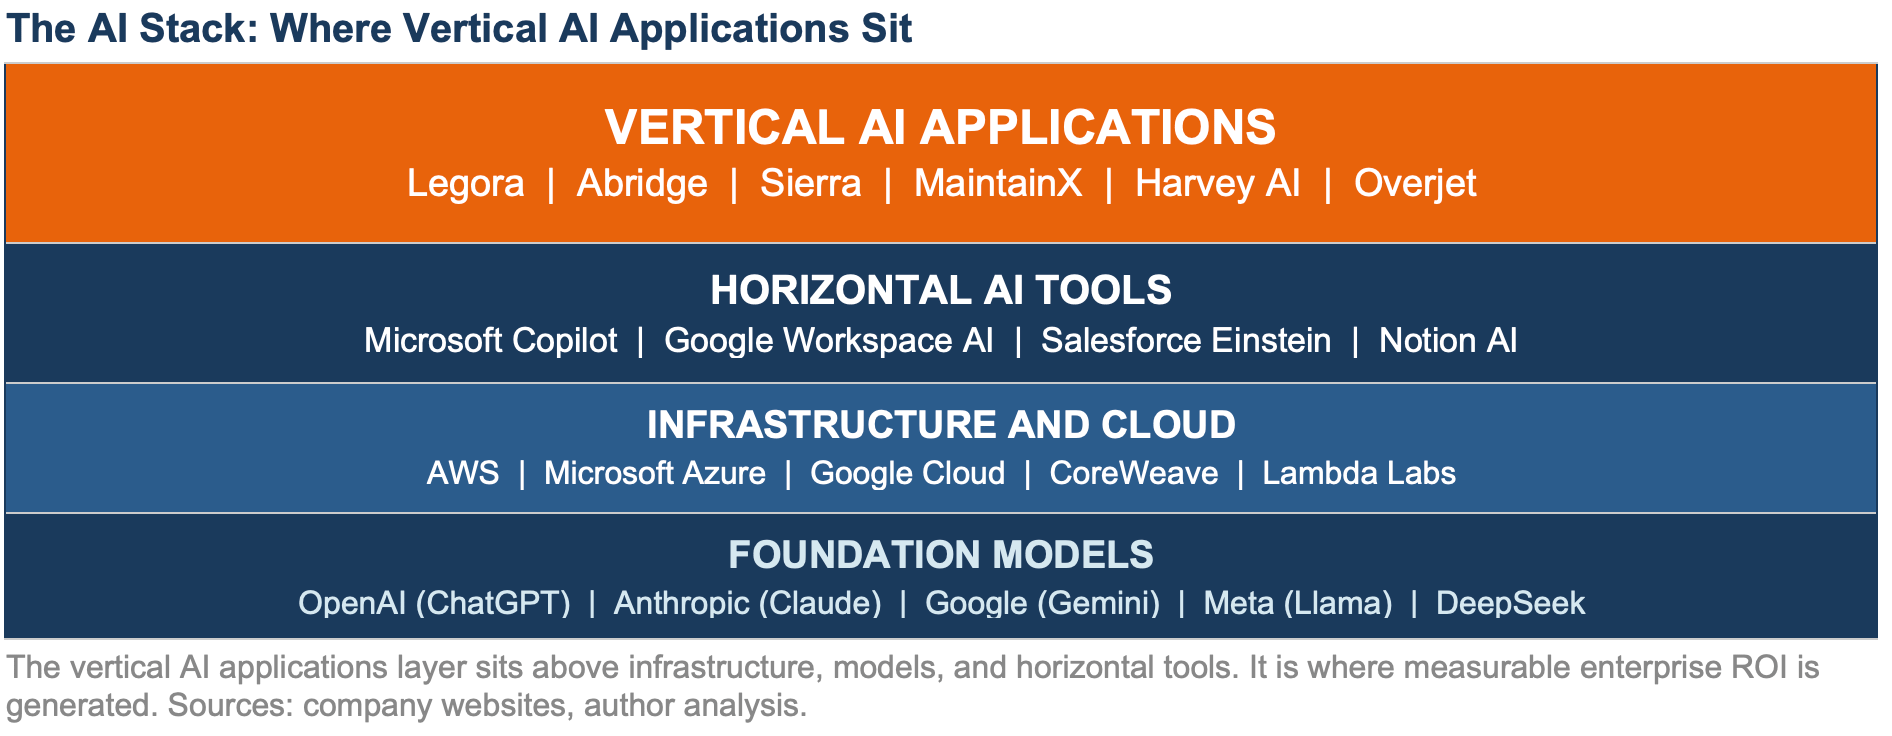
A Horizontal AI application gives users the capability and leaves the application to them. Microsoft Copilot, Google Workspace AI, and Notion AI all fit this description. They are useful. They are not vertical.
A Vertical AI application is purpose-built for a specific industry workflow. A vertical AI provider typically doesn’t develop AI foundation models; it uses them. They are not raising money to build data centers; they are renting space in data centers. They are delivering real value - replacing expensive labor, cutting process execution time, and increasing revenues for their customers. They are also growing at a pace the enterprise software applications market has never seen - EVER.
Vertical AI companies have some major advantages over traditional SaaS companies:
When Thomson Reuters adds AI features to Westlaw, or Veeva adds AI to its CRM, it’s an improvement, but, without major investment, the product architecture, pricing model, and organizational design remain anchored in a pre-AI world. A Vertical AI-native company’s products are built on AI from day one.
The Vertical AI Business Model Is Different
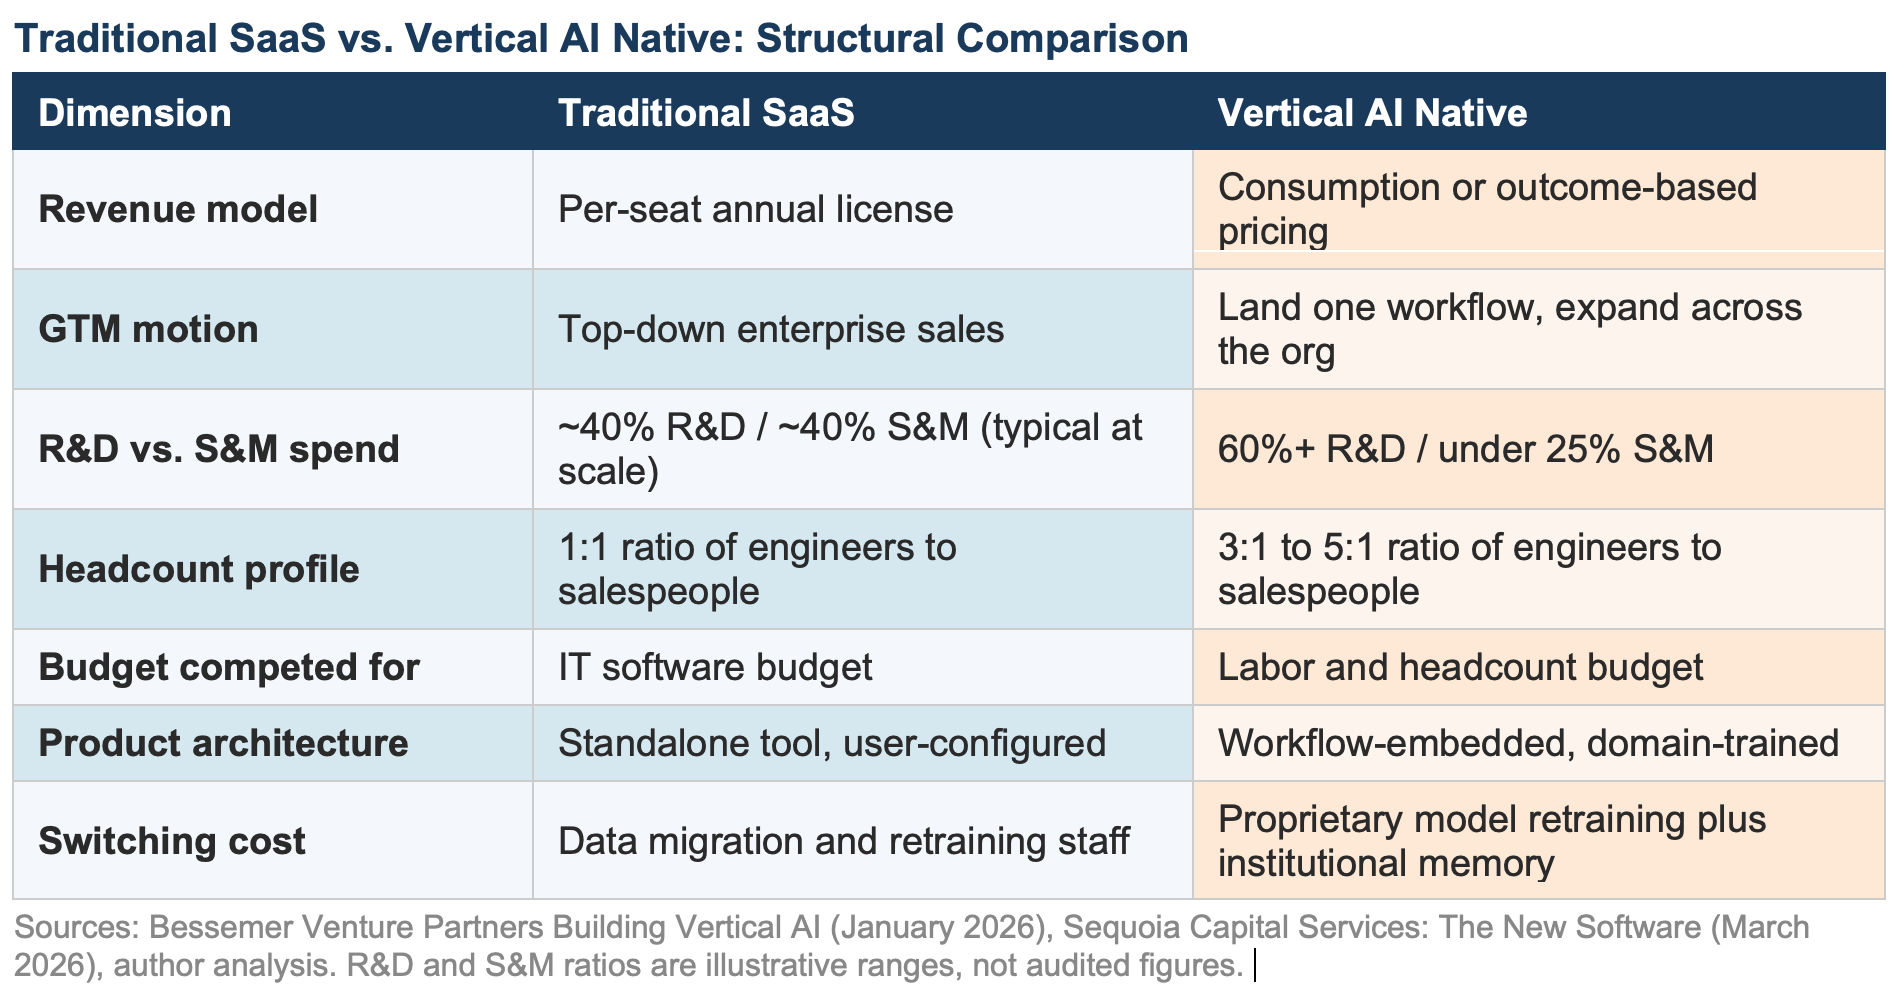
Bessemer Venture Partners has invested over $1 billion into AI-native startups since 2023. Bessemer’s January 2026 Vertical AI playbook clearly articulates why the Vertical AI business model is different:
Traditional SaaS companies target IT/software budgets. Vertical AI companies target labor budgets.
In the US, the total labor market is roughly 10 times the size of the enterprise software market. The best Vertical AI applications replace or radically reduce the cost of skilled professional labor. A Vertical AI company’s operating model follows from that:
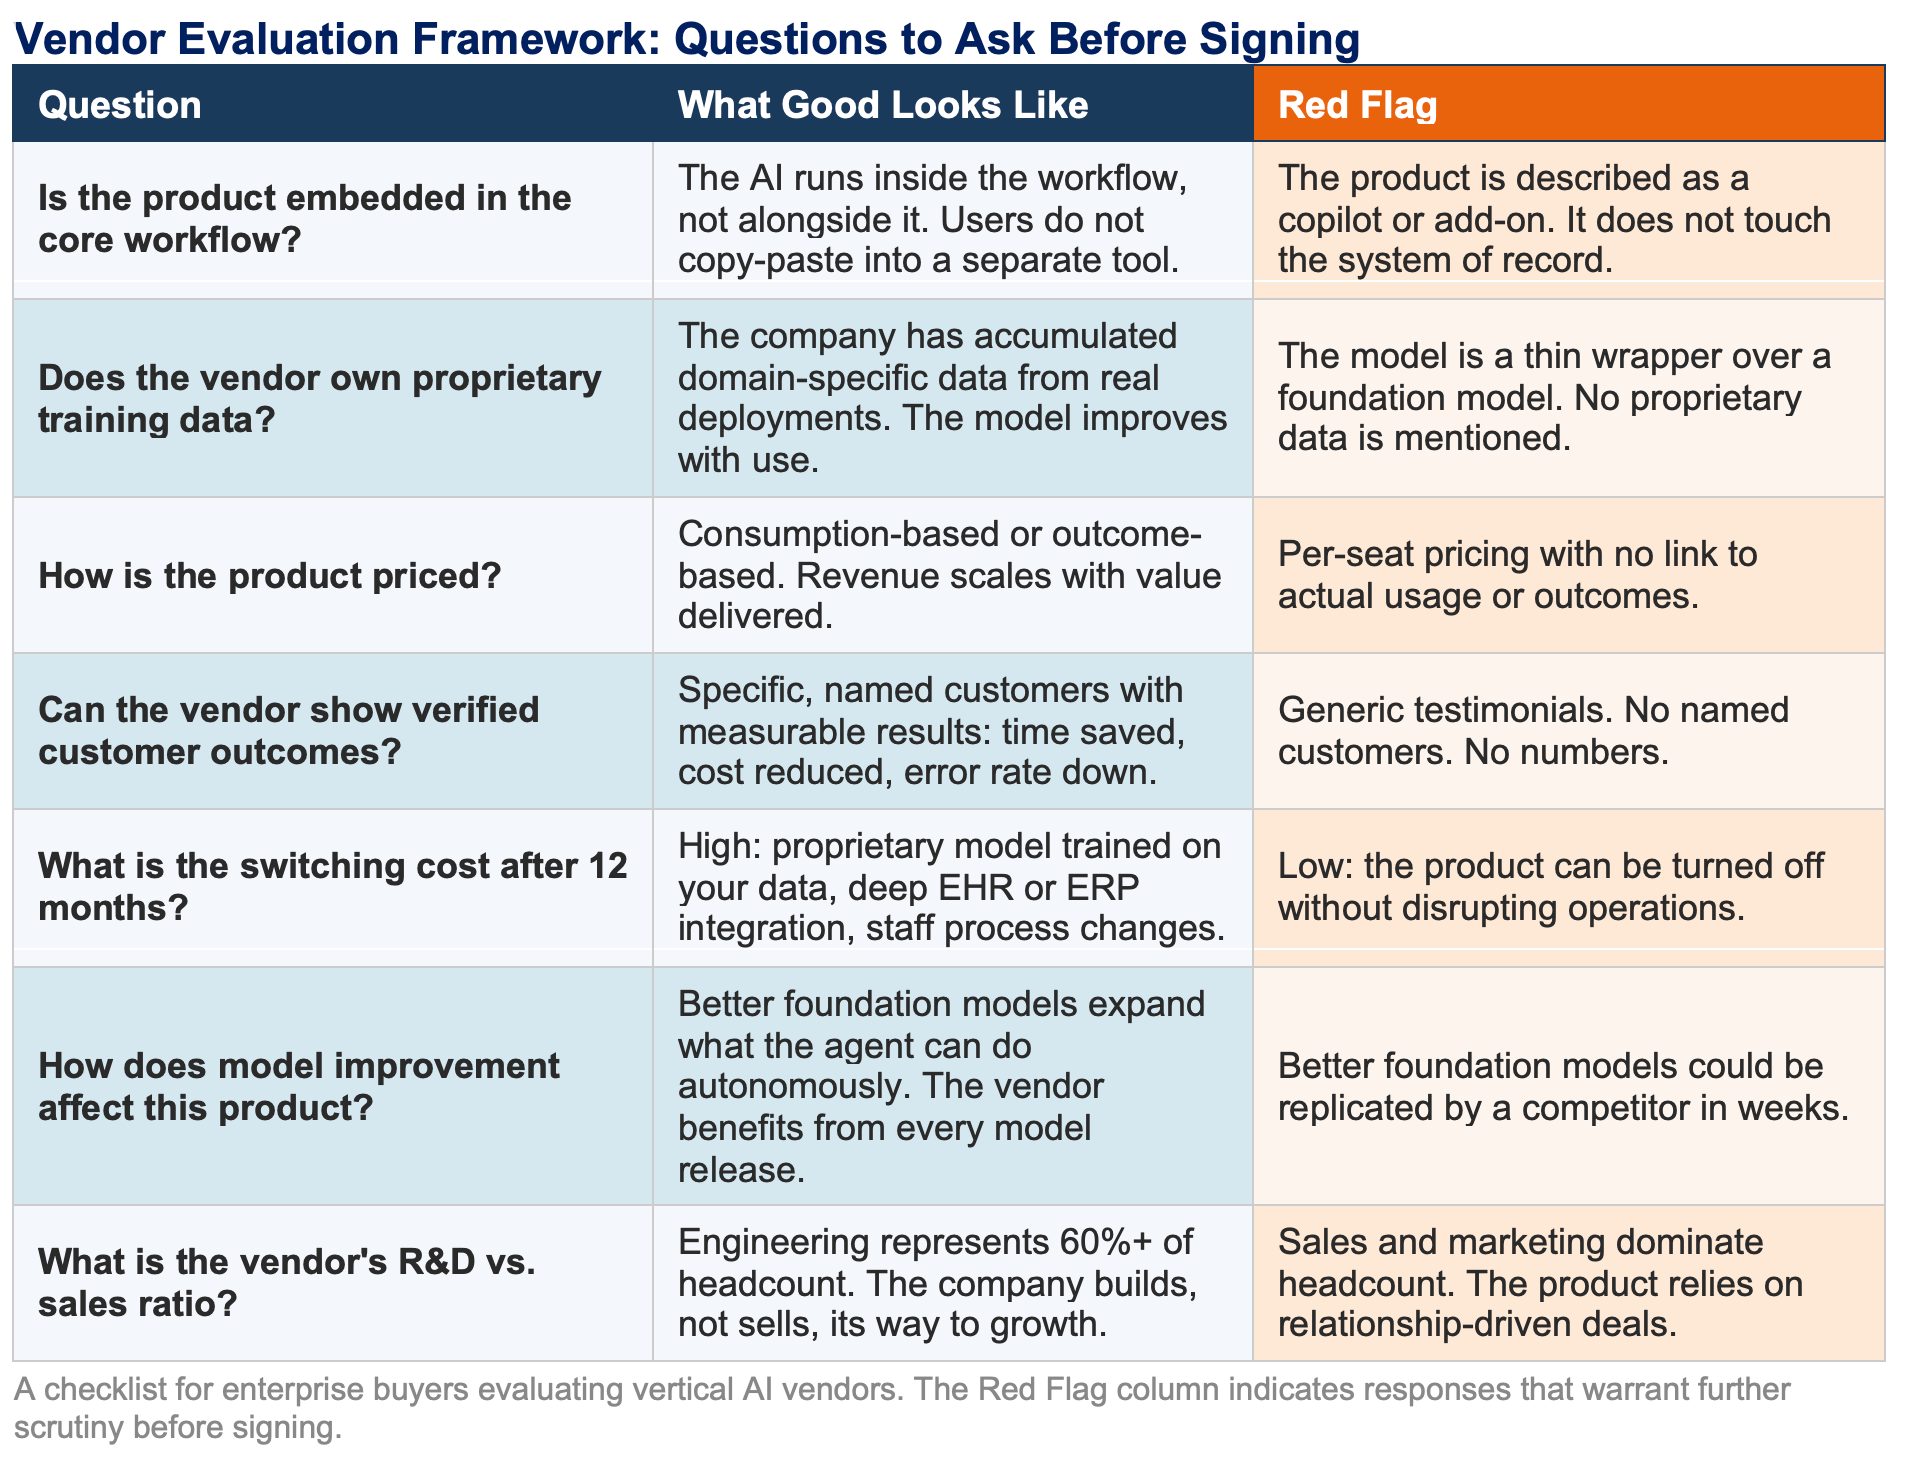
Pricing is consumption-based or outcome-based rather than per-seat. That means revenue scales with the actual value delivered, not end-user seats.
Go-to-market is workflow-led: the first deployment covers one workflow, earns trust, and subsequent workflows follow.
Engineering typically represents 60 percent or more of headcount.
Sales and marketing usually account for less than 25 percent of operating expenses.
Vertical AI products are built differently.
They don’t sit on top of existing systems.
They are embedded inside the workflow.
They ingest proprietary data and build domain-specific models that improve with every interaction.
That is the moat. Displacing an embedded Vertical AI application does not just mean switching software. It means abandoning the institutional memory that is embedded in a custom-trained AI-driven workflow model.
Sequoia Capital’s March 2026 thought piece, “Services: The New Software”, makes the case for Vertical AI applications quite clearly:
Every founder building an AI tool is asking the same question: What happens when the next version of Claude makes my product a feature? They’re right to worry. If you sell the tool, you’re in a race against the model. But if you sell the work, every improvement in the model makes your service faster, cheaper, and harder to compete with. A company might spend $10K a year for QuickBooks and $120K on an accountant to close the books. The next legendary company will just close the books.
Funding Is Flowing into Vertical AI Companies
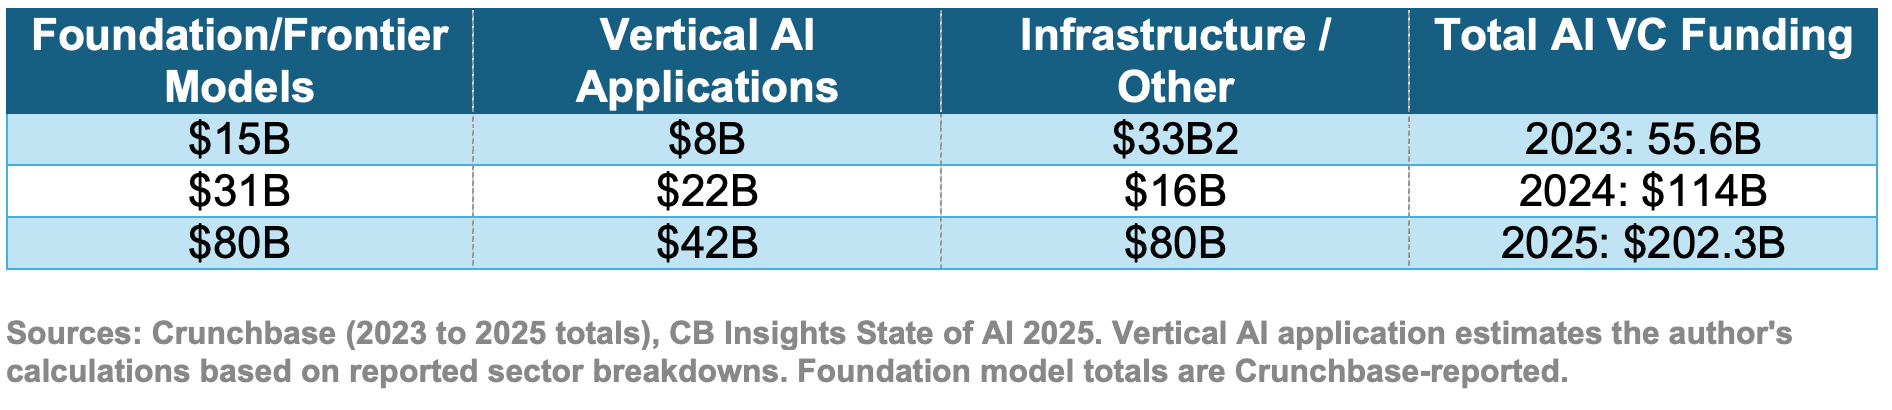
Vertical AI companies raised ~$42 billion in 2025, up from roughly $22 billion in 2024 and $8 billion in 2023. In 2023, most VC dollars chasing vertical AI went to early-stage bets. By 2025, VC investing in vertical AI was all about big bets: mega-rounds of $100 million or more accounted for 79 percent of all AI funding, per CB Insights. Late-stage deal sizes for vertical AI companies have expanded sharply. By 2025, multiple vertical AI companies were closing rounds of $300 million or more in a single year — Harvey raised two such rounds in 2025 alone.
The Explosion of Vertical AI Unicorns
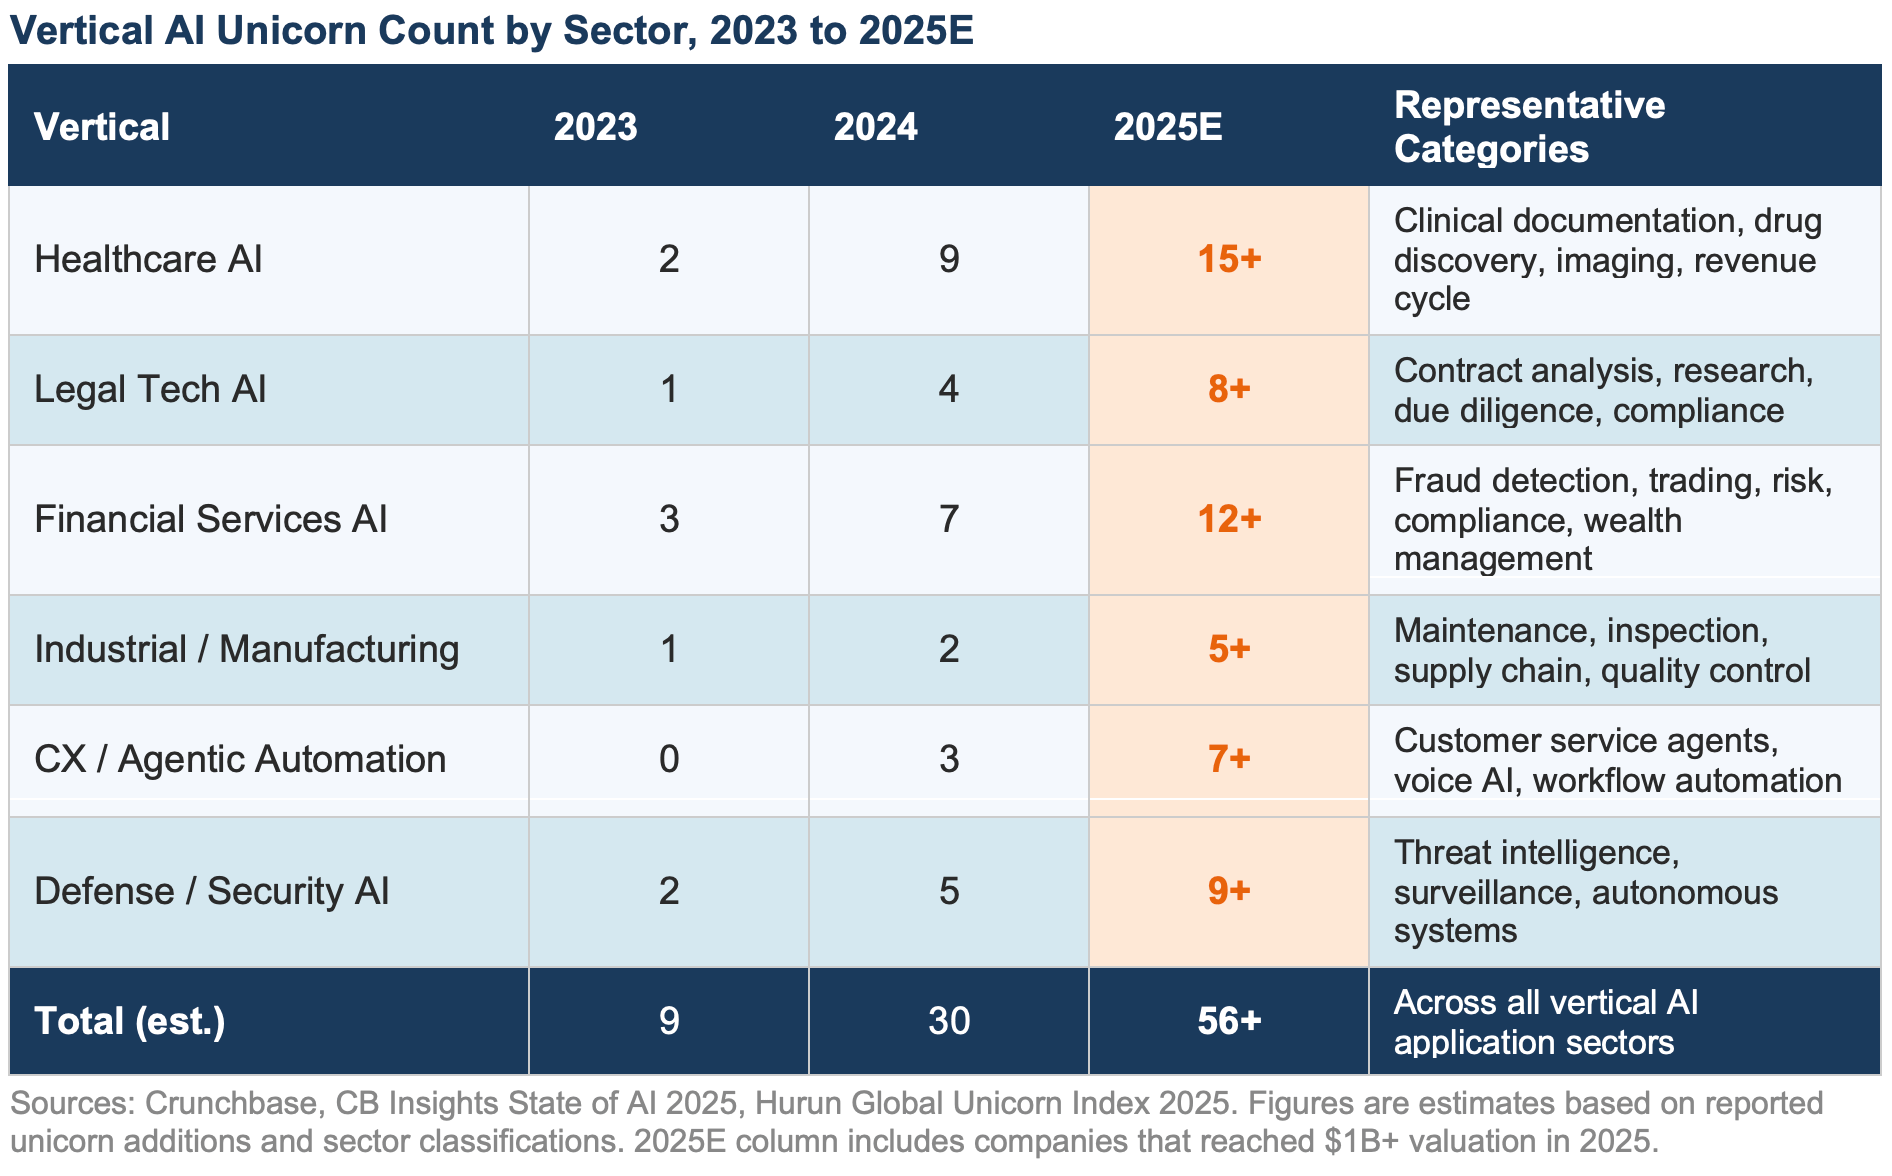
The count of vertical AI unicorns has grown sharply since 2023:
CB Insights reports that the leading 2025 categories for new unicorn creation included healthcare AI (10+ companies) and AI infrastructure. Healthcare was the single largest sector for new unicorn additions for multiple months in 2025.
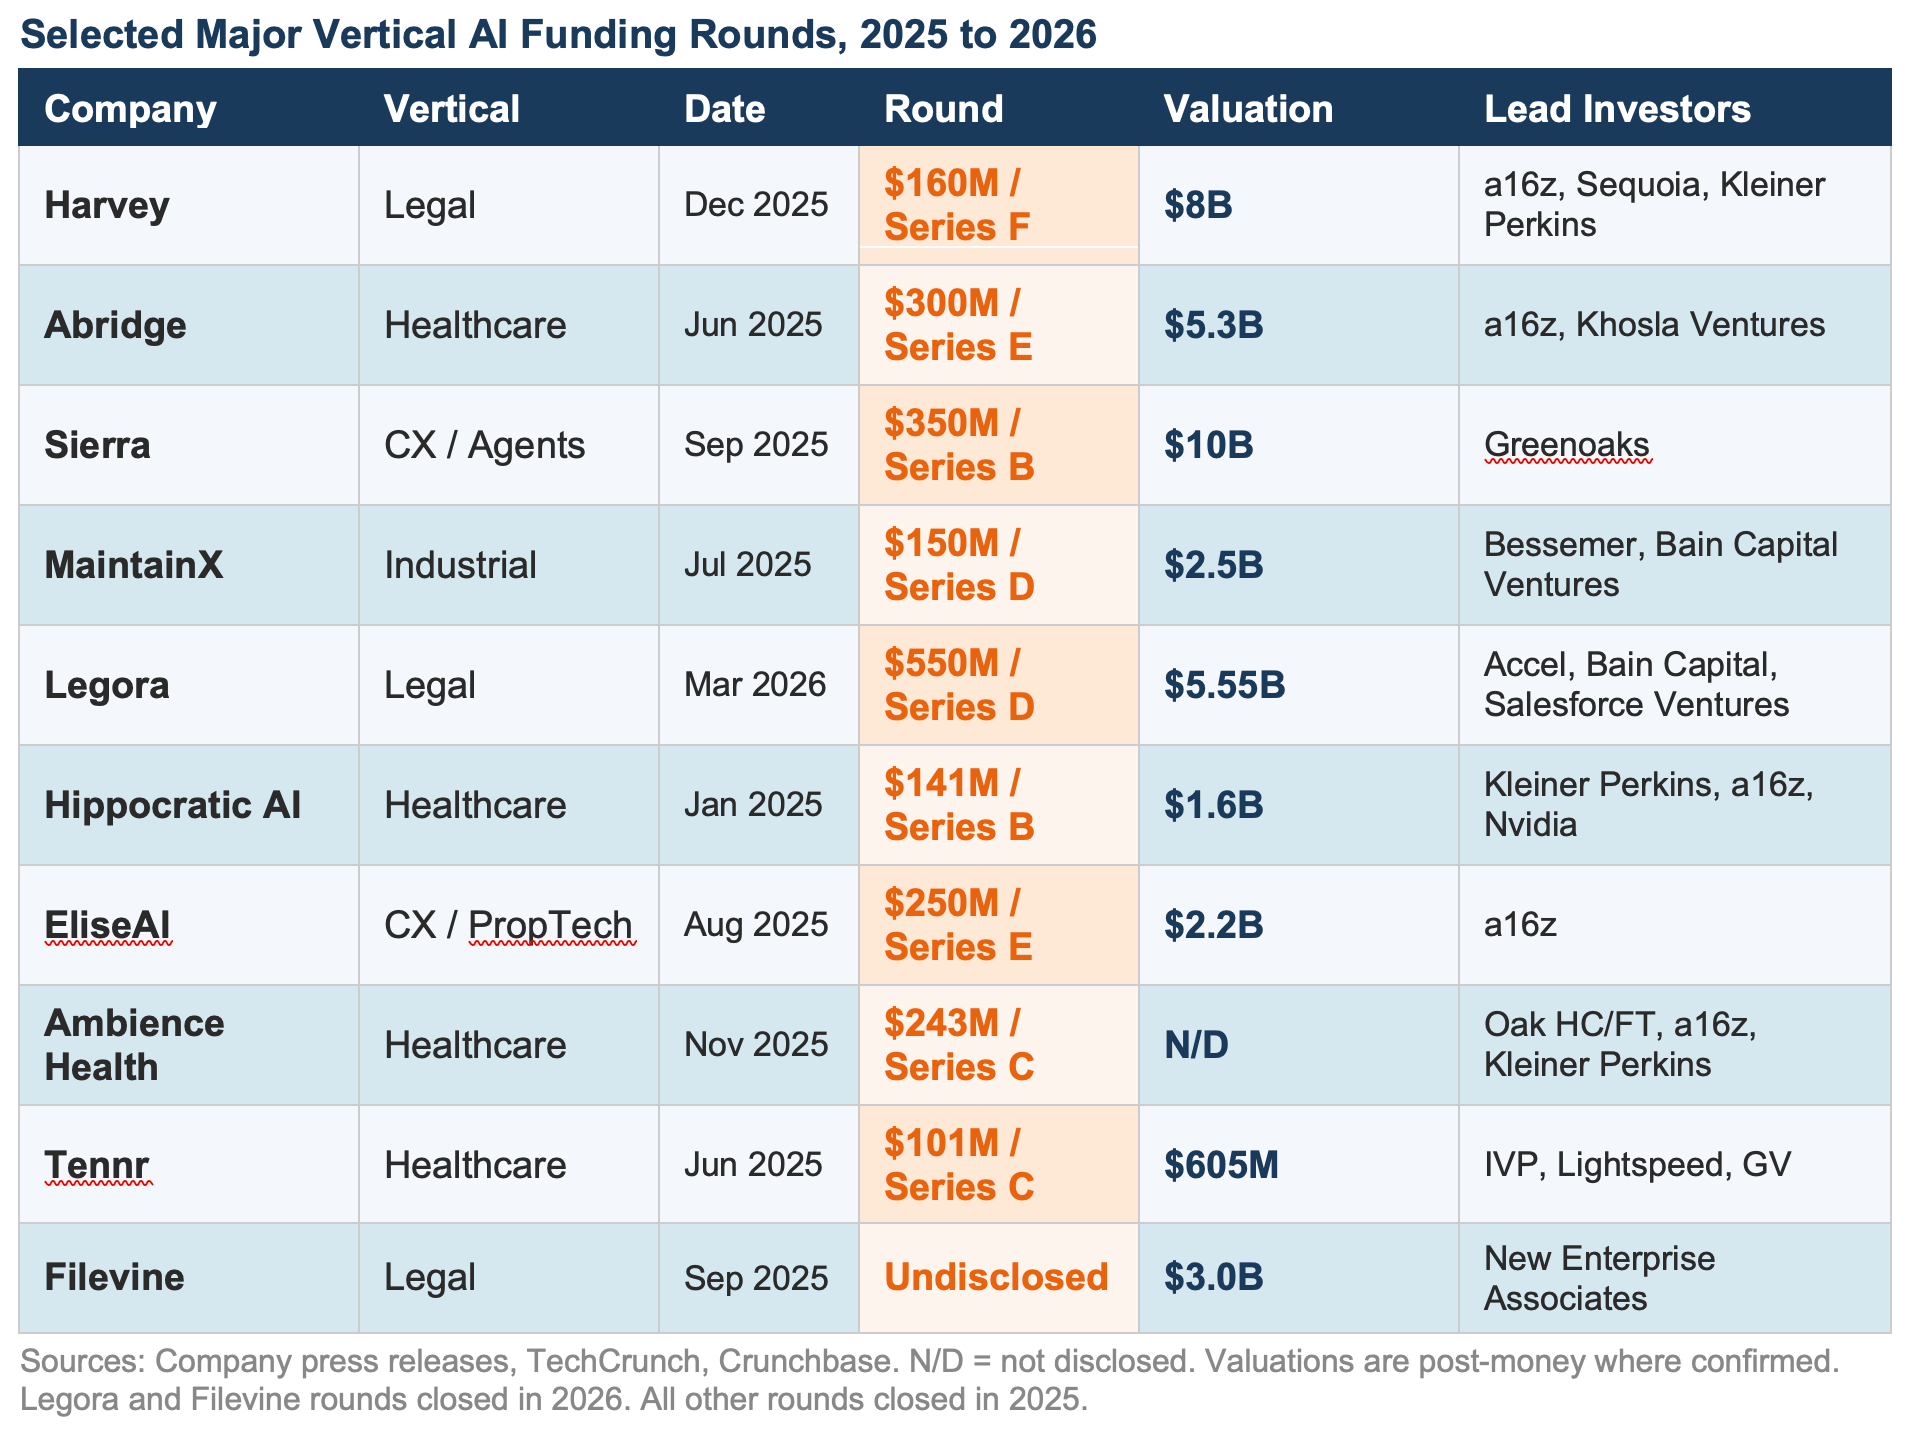
Legal tech produced fewer unicorns in absolute terms but at higher average valuations. Harvey crossed $8 billion in confirmed valuation in December 2025. Legora reached $5.55 billion in March 2026. Filevine joined the unicorn board at $3 billion in September 2025. The legal vertical has gone from zero major AI unicorns in 2022 to at least eight by early 2026.
Financial services AI has the largest unicorn count by sector, but is more fragmented. The sector’s AI incumbents, which include fraud detection platforms, trading systems, and compliance tools, adopted machine learning early. Scale Ventures argues that this is because JPMorgan alone spends more on technology each year than all US law firms combined. The ROI from switching to AI-native tools is lower where incumbents already run on sophisticated ML.
Industrial and manufacturing AI is at an earlier stage but is accelerating. MaintainX reached a $2.5 billion valuation in July 2025. The sector’s pipeline of future unicorns is deep: Hurun’s 2025 Gazelles Index identified manufacturing and industrial operations as a leading sector for pre-unicorn companies likely to reach $1 billion by 2028.
The pattern across verticals is consistent:
Sectors with high labor costs, low prior technology adoption, and language-heavy workflows arrived first. Legal and clinical documentation were the opening wave. Industrial operations, financial back-office, and government services are the next. Each wave is accelerating faster than the one before it.
Four Companies That Help to Define Vertical AI Applications
Harvey - Legal
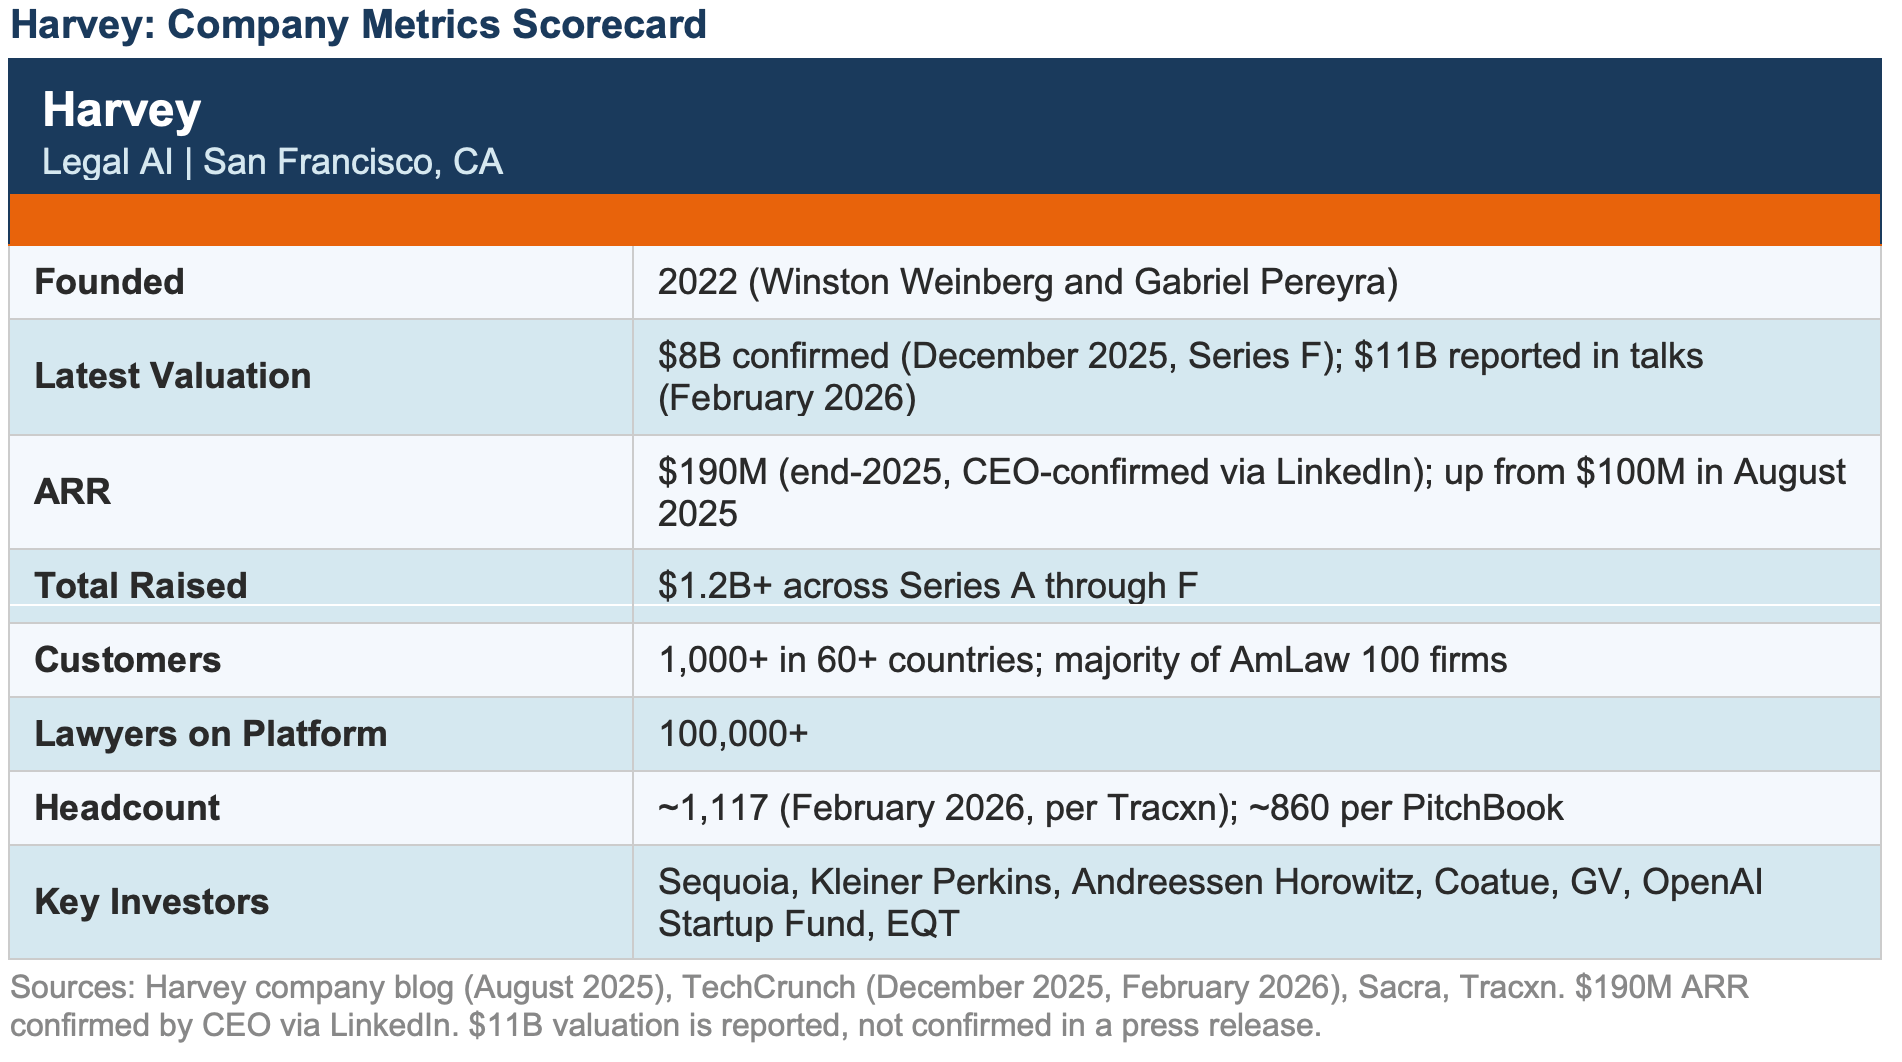
Harvey is the most data-rich vertical AI company in the legal sector. It was founded in 2022 by Winston Weinberg, a former antitrust and securities litigator at O’Melveny and Myers, and Gabriel Pereyra, a research scientist from Google DeepMind and Meta. The origin story is well documented: Weinberg cold-emailed Sam Altman in 2022 after seeing GPT-3 and recognizing its potential for legal workflows. Harvey became one of the OpenAI Startup Fund’s first investments.
Products & Technology
Harvey’s architecture is deliberately modular:
Rather than routing every query through a single model, the platform orchestrates different AI models depending on the task: one for document analysis, another for legal research, and a third for contract drafting.
A no-code Workflow Builder lets law firms construct their own task-specific agents without Harvey’s involvement.
That configurability, combined with deep integration with document management systems and firm-specific data, makes displacement difficult.
One client quote from Harvey’s website captures the stickiness:
“If we took Harvey away from our staff, there’d be a riot.”
Financials
Harvey reached $100 million in ARR in August 2025, 36 months after its founding. By the end of 2025, ARR had grown to $190 million, up from $50 million at the end of 2024. Harvey serves 1,000-plus customers across 60+ countries, including a majority of AmLaw 100 firms and the corporate legal departments of Comcast, Verizon, KKR, and PwC. As of February 2026, Harvey was in talks to raise $200 million at an $11 billion valuation led by Sequoia and GIC, following a confirmed $8 billion valuation in December 2025.
M&A Adds Functionality and Access to New Markets
Harvey Lume AI and Hexus in early 2026, the latter to accelerate its in-house legal offerings. Harvey has opened offices in Dublin, Paris, and Bangalore and has launched the Harvey Academy, a certification program for legal AI. Harvey’s headcount stood at approximately 1,117 as of February 2026, up from 350 in August 2025.
“Targeting the legal market with generative AI kind of felt like a bullseye. For one thing, the industry is big — a $400 billion market in the US.”
Sequoia Partner Pat Grady
Abridge - Healthcare
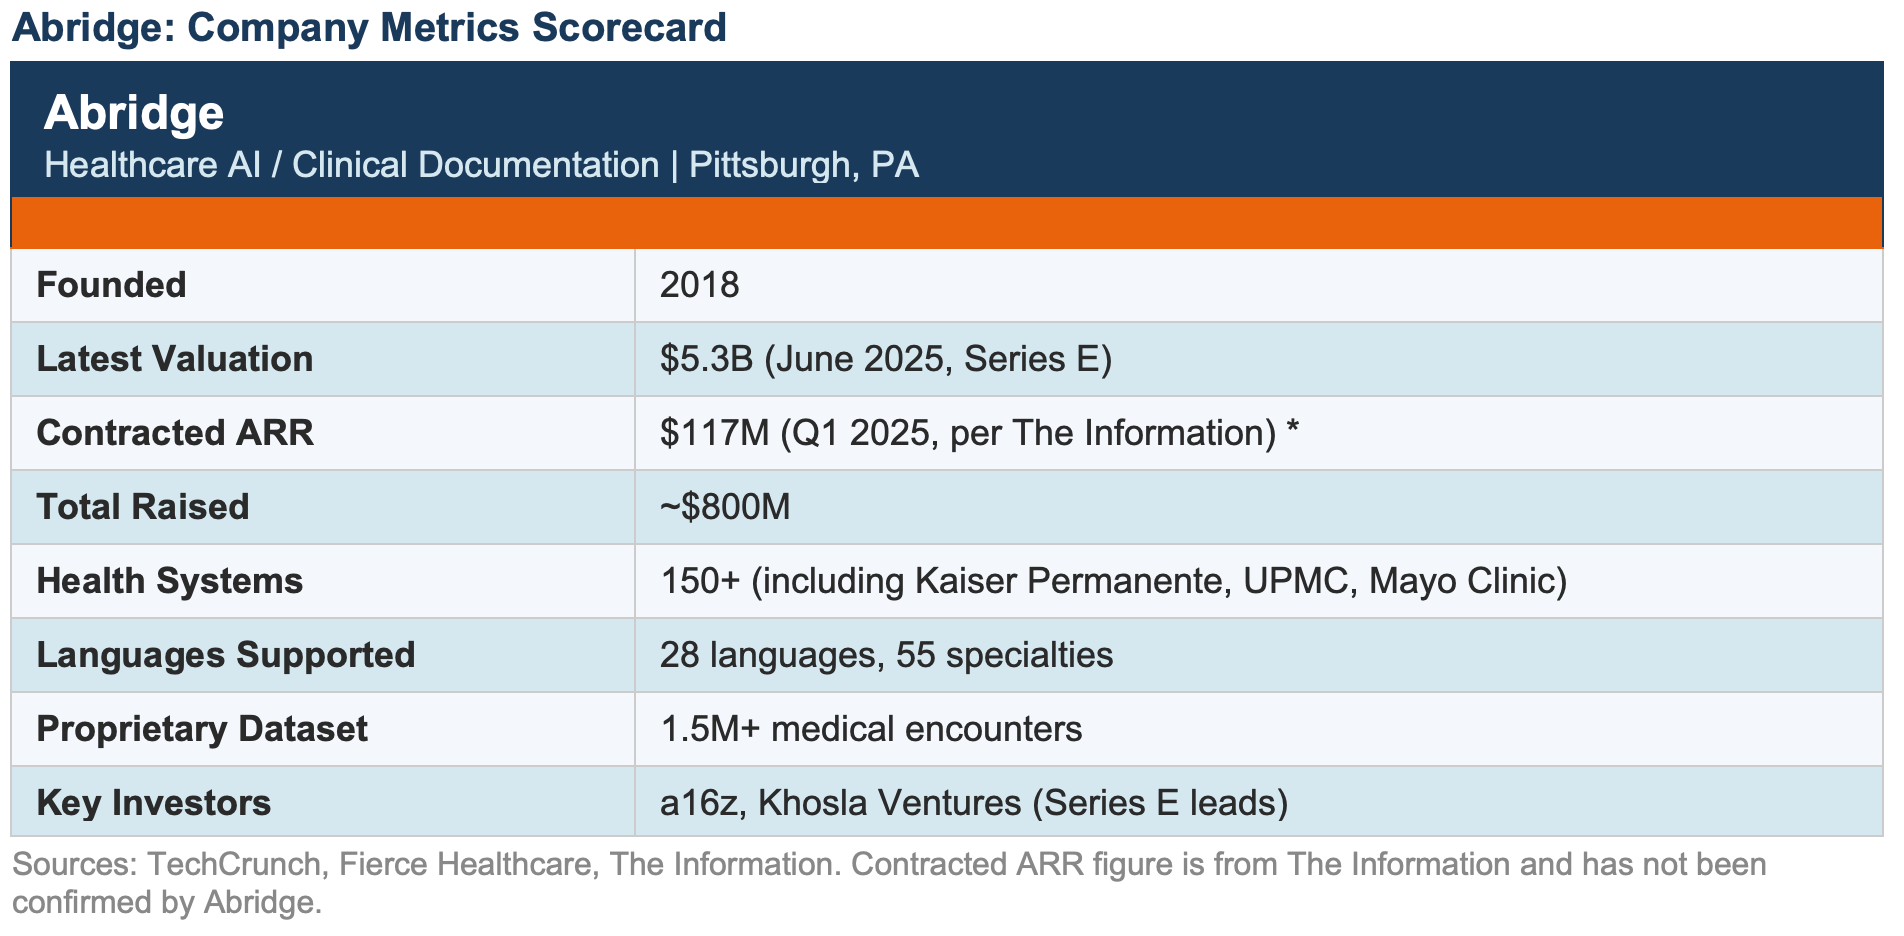
Abridge is the most mature company in this cohort. Founded in 2018 by cardiologist, Founder, & CEO Shiv Rao, Abridge builds ambient AI that converts physician-patient conversations into structured clinical documentation in real time. It covers 55 specialties and works in 28 languages.
Financials & Client Base
Abridge raised $300 million in a Series E led by a16z and Khosla Ventures in June 2025, at a $5.3 billion valuation, doubling from $2.75 billion in February 2025. The total raised is approximately $800 million. Contracted ARR stood at $117 million in Q1 2025, according to The Information.
The client base includes 150-plus health systems, including:
Kaiser Permanente across 40 hospitals
UPMC, serving 12,000 clinicians by 2026
Johns Hopkins
Mayo Clinic
Duke Health
Memorial Sloan Kettering
The Wall Street Journal described Abridge as the widely considered leader in the AI-powered medical scribe market.
Products & Technologies
A general-purpose transcription tool produces a transcript. Abridge produces a structured SOAP note, formatted for the relevant specialty, integrated with the EHR, and surfaced without the physician having to touch a keyboard. Abridge has expanded the product suite to include revenue cycle and prior authorization. A partnership with Highmark Health has reduced prior authorization timelines from weeks to minutes.
Once a health system has trained clinicians, integrated the EHR, and built quality benchmarks around Abridge’s output, the cost of switching is high. That is a durable moat.
“Every medical conversation is rich with the signals our healthcare system depends on. Abridge activates those signals in the background, silently handling the complexity so clinicians can focus on the human moments that matter.”
Abridge Founder & CEO Shiv Rao
Sierra - Customer Experience
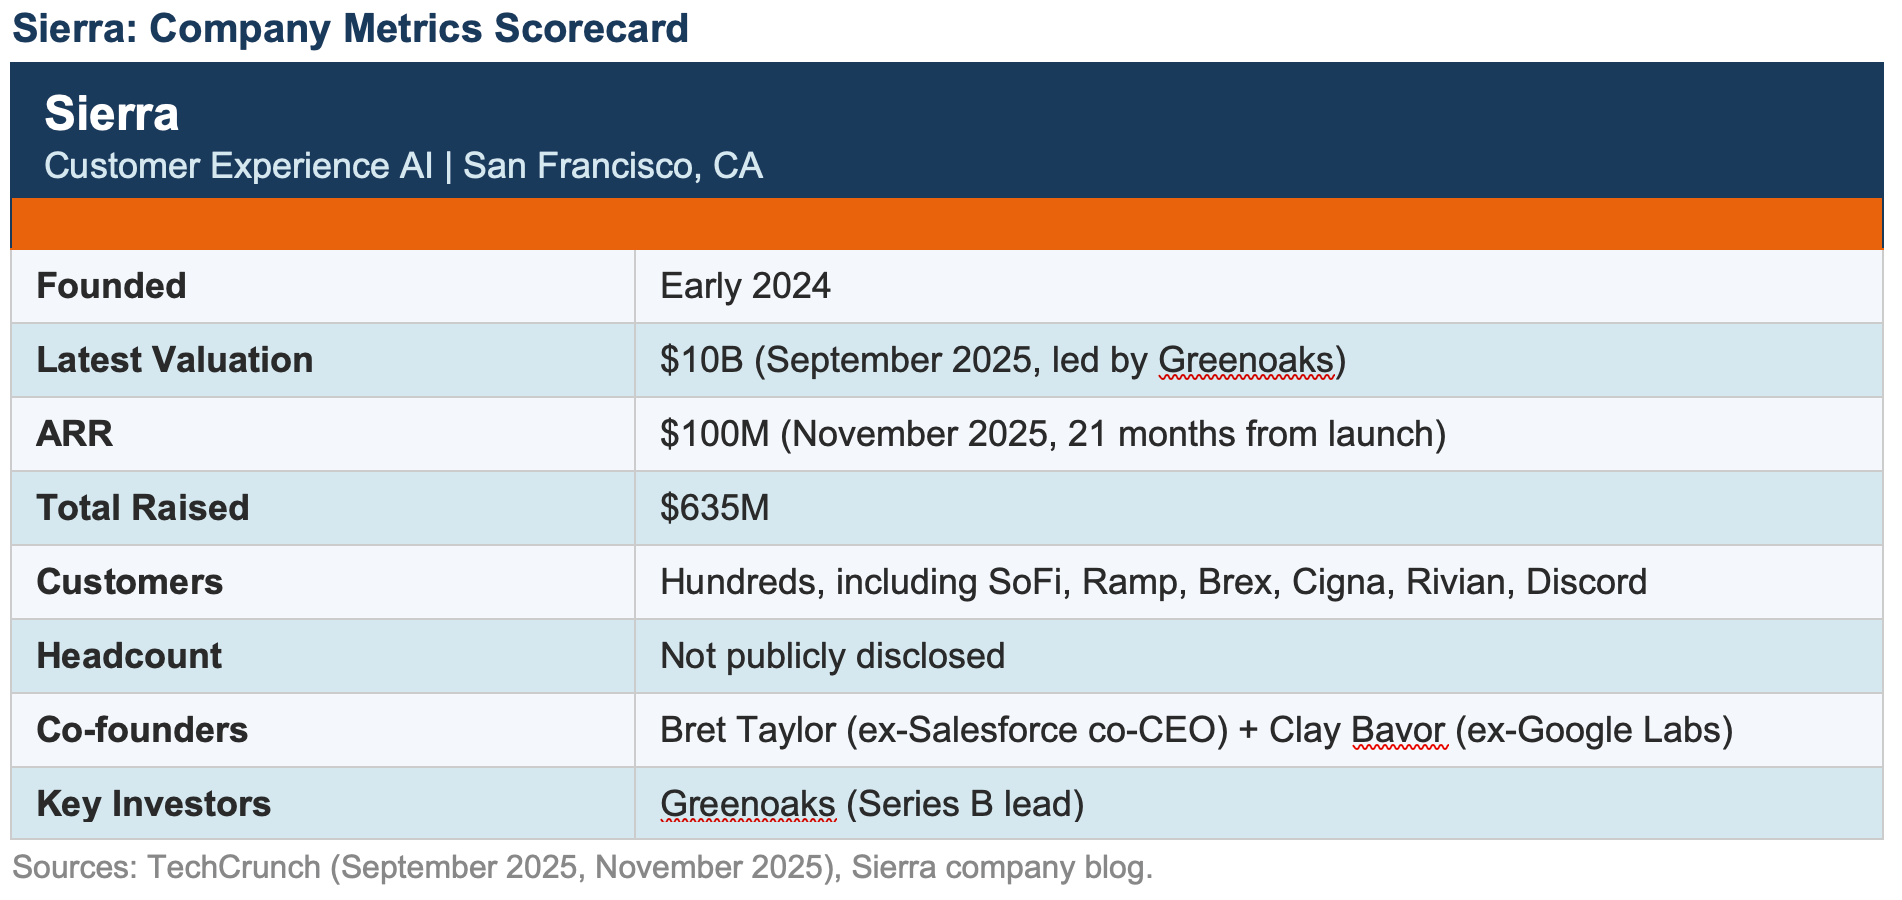
Founded in early 2024 by Bret Taylor (former Salesforce co-CEO and OpenAI board chair) and Clay Bavor (former head of Google Labs), Sierra builds AI agents that handle customer-facing interactions. These are not deflection bots. They resolve issues, process transactions, and manage complex customer journeys across voice, text, and web from a single deployment.
Financials & Customers
Sierra raised $350 million in September 2025, led by Greenoaks, at a $10 billion valuation, bringing the total raised to $635 million. In November 2025, Sierra announced that it had reached $100 million ARR, 21 months after launch. Taylor and Bavor wrote:
“That’s a heck of a lot quicker than we expected and makes Sierra one of the fastest-growing enterprise software companies in history.”
Customers include SoFi, Ramp, Brex, ADT, Cigna, SiriusXM, Deliveroo, Discord, Rivian, and Tubi.
Products & Technologies
Sierra’s Agent OS architecture allows enterprises to define their agent’s persona, policies, and escalation logic once and deploy across all customer channels without additional integration work. The company acquired Receptive AI for voice capabilities in March 2025.
Sierra’s focus on customer experience and the accumulation of trust with its customers over time are its moats. Brands learn how much autonomy to grant an AI agent only through real deployment at scale. Once they have calibrated behavior, persona, and escalation thresholds to their specific customer base, rebuilding that institutional knowledge on a different platform is a major undertaking.
“The market is gigantic” for vertical and domain-specific agents and has wondered aloud whether the agent era might produce “the first trillion-dollar applied enterprise software company.”
Sierra CEO Brett Taylor
MaintainX - Industrial
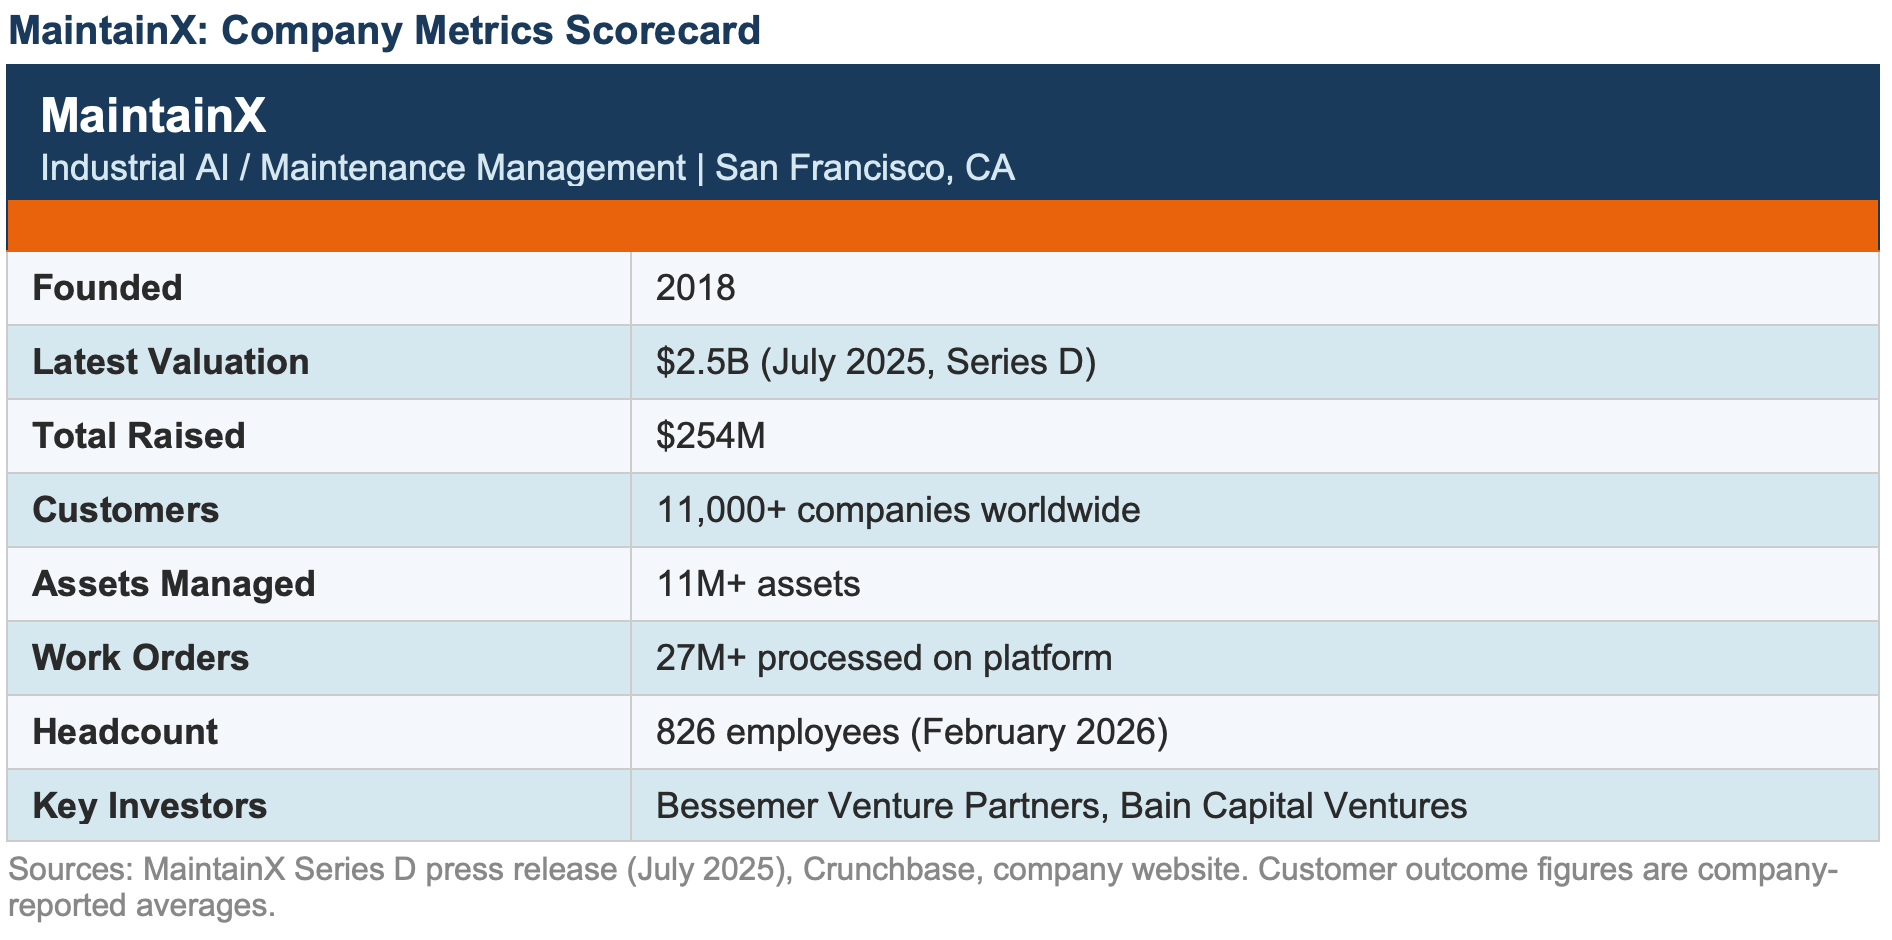
MaintainX covers a category that receives less venture attention than legal or healthcare but represents a large and underserved market: maintenance management and asset performance for physical-asset-intensive industries. Manufacturing plants, warehouses, utilities, food production, and aviation ground support all depend on equipment that, when it fails, costs money:
Equipment failures cost an estimated $1.4 trillion annually worldwide.
Most companies managing those assets still use spreadsheets, paper orders, and legacy CMMS tools built in the 1990s.
Financials, Customers, & Employees
MaintainX raised a $150 million in Series D funding in July 2025, led by Bessemer and Bain Capital Ventures at a $2.5 billion valuation, up from $1 billion in December 2023. The total raised to date is $254 million. MaintainX serves 11,000-plus companies worldwide, has processed more than 27 million work orders, manages over 11 million assets, and records more than 370,000 safety procedures annually. The company employs 826 people as of February 2026.
Products & Technology
MaintainX uses AI to create a powerful data network effect:
MaintainX’s layer sits on years of proprietary operational data from real deployments, including work-order histories, asset-failure records, and maintenance logs.
When MaintainX recommends a preventive maintenance interval or flags an anomaly, it draws on patterns from millions of similar assets across the entire platform.
A generic AI assistant applied to maintenance tasks cannot replicate that.
Common customer outcomes include:
34 percent reduction in unplanned downtime
15 percent increase in production capacity
32 percent savings in monthly maintenance costs
The company holds the number one ranking in Enterprise Asset Management and CMMS on G2 and was named a Leader in the Verdantix 2025 Green Quadrant for CMMS, the sector’s most-cited analyst benchmark.
“Equipment failures cost companies $1.4 trillion annually, and many still rely on outdated tools. We built MaintainX to change that.”
MaintainX CEO Chris Turlica
“MaintainX has achieved remarkable product-market fit by addressing a critical challenge that affects virtually every physical asset-driven industry.”
Bessemer partner Byron Deeter
Key Takeaways
Structural advantages of vertical AI
Vertical AI competes for labor budgets. Those are ten times larger than IT software budgets, giving the category a TAM that horizontal tools cannot reach.
Proprietary data compounds with every deployment. The switching cost is not a software migration. It is an institutional knowledge migration.
Consumption and outcome-based pricing align vendor and customer incentives. Revenue scales with verified value, not seat counts.
Every improvement in foundation models expands the scope of vertical agents. Companies selling tools face commoditization as models improve. Companies embedded in workflows do not.
What should enterprise buyers do now?
Audit your technology spend for any workflow that is high-labor, high-repetition, and domain-specific. Those are the best candidates for a vertical AI deployment.
Evaluate AI-native companies alongside incumbent vendors in every category review. The performance gap between AI-native and bolt-on is widening every quarter.
Insist on outcome-based commercial structures. A vertical AI vendor that will not price based on verified performance is a red flag.
Start narrow. Deploy one embedded workflow, measure against clear baselines, and expand. The land-and-expand model works in both directions.
In Conclusion
The companies we’ve profiled here are not outliers. In fact, these companies have unique advantages:
They are run by teams with domain expertise.
Their products are built on AI-native architectures.
In operation, their products compound revenue, customer relationships, and proprietary data at a pace that incumbents cannot match.
Companies at the cloud and infrastructure layer, such as OpenAI, Anthropic, Google, and Microsoft, will continue to produce big headlines. Vertical AI companies will deliver AI-native products that produce increasingly high ROI.
The AI to ROI Podcast
If you want to listen to the latest news in AI with more detail and analysis, Ray and Peter break down the big story of the week on the AI to ROI podcast. We also interview leaders at AI companies and in mid- to large-sized enterprises about their challenges and successes in deploying AI projects. Click here to listen or subscribe using your favorite podcasting app.
Yes, Charlotte, you are right on target! I think vertical AI is the layer that's the biggest winner in the AI stack. Sadly, it's largely ignored by the trade press. It's where most of the success stories actually live. BTW, customers are getting used to your thesis in a hurry - much faster than I would have expected a year ago.
Vertical AI Is Non-Rival. That's the Bug, Not the Feature.
Rike and Buchanan are right that vertical AI is where ROI is showing up. They've missed why it won't stay there.
Economic goods come in two flavors. Rival goods can only be consumed by one party — a factory, a customer relationship, a distribution network. Non-rival goods can be replicated infinitely at near-zero marginal cost — software, models, code.
Vertical AI is non-rival. That is the entire problem.
Harvey's workflow builder, Abridge's SOAP-note pipeline, Sierra's agent OS — every one of them runs on foundation models any competitor can rent by the hour, trained on data any competitor can buy or scrape, sold into industries with no structural barriers to a second entrant. The "moat" of institutional memory takes 18 months to build and a sharper competitor 12 to replicate. Margins compress. Pricing collapses to cost-plus. The arbitrage closes.
The only durable AI returns will accrue to rival, excludable assets — the customer, the distribution, the brand, the physical footprint. You cannot replicate a hospital. You cannot fork a law firm. You cannot rent a forty-year distribution network by the GPU-hour.
The IBO inverts the trade. Don't sell intelligence into the workflow. Buy the workflow, then install the intelligence.
Vertical AI is the fourth wave. The fifth is operators with capital who skip the licensing model entirely.
Sequoia called it services as the new software. We call it ownership.